If you’ve been putting off your mortgage search because you think summer is the only time to buy or refinance, you’re making a mistake. The truth is that winter often holds the best opportunities for regular homeowners who just want a fair deal. While everyone else is busy with holidays, snow days, and year-end distractions, the mortgage market gets quieter. And in that quiet, you can find advantages that simply don’t exist during the busy spring and summer months.
Let’s start with the most basic fact: fewer people shop for mortgages in December, January, and February. That means fewer buyers are competing for the same houses, and it also means lenders are less overwhelmed. When a loan officer has a lighter workload, they have more time to actually answer your questions, explain the numbers, and work through any hiccups in your application. You are not just a ticket number in a long line. You get real attention, which matters when you’re trying to make sure you understand every cost and condition before you sign anything.
Another reason winter is your friend has to do with lender quotas. Most mortgage lenders and banks have annual targets for how many loans they want to close. When the year is winding down, many still have room to go on their goals. That gives them a strong reason to offer you better terms, such as a slightly reduced rate or lower closing costs, to get your business locked in before December 31st. You can use this to your advantage. Simply asking “Is there any room to improve this offer?” can often lead to a better deal during these final weeks. In the summer, when demand is high, you won’t get that same flexibility.
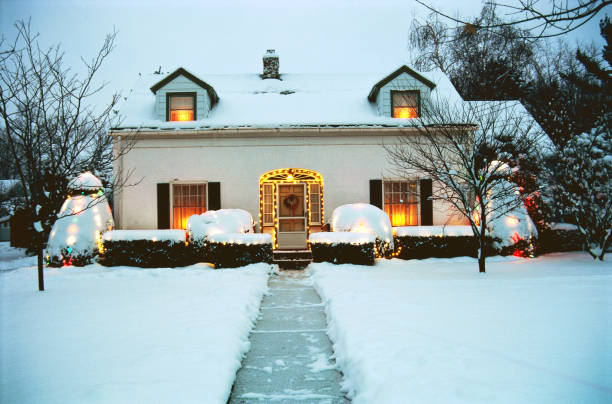
The winter weather also plays a role in your favor, though not in a way you might expect. When the ground is frozen and the days are short, there’s far less foot traffic at open houses. Sellers who list their homes in the winter are usually serious about moving. They aren’t just testing the waters or hoping for a bidding war. They want to close, and they’re often willing to negotiate on price or throw in concessions like covering some of your closing costs. A lower purchase price means a smaller loan, which means lower monthly payments for you. That’s a simple math win that few people talk about.
Rates themselves also tend to move in your favor during the colder months, though not in a guaranteed way. Historically, mortgage rates have often dipped in winter because there is less demand for borrowing. Banks want people to borrow money all year round, so they sometimes sweeten the pot when fewer people are signing up. December and January have seen some of the lowest average rates in recent years. That doesn’t mean you should wait forever, but it does mean that shopping in winter gives you a better chance of catching a dip than holding off until spring when everyone and their neighbor is suddenly looking for a new home.
There is one important thing to watch out for, and that’s the holiday slowdown. The week between Christmas and New Year’s Day can be tricky because many appraisers, title companies, and even lender offices run on reduced hours. If you need to close fast, you might hit a snag. The fix is simple: start your process in early December or even late January. Give yourself extra time for appraisals and paperwork. A longer timeline is fine. What matters is that you get the better deal, not that you rush into a bad one because you’re pressed for time. Think of winter as your chance to be slow, careful, and thorough. That’s exactly how a smart borrower should operate.
Also, don’t forget about your own schedule. In the summer, you’re likely juggling vacations, kids out of school, and weekend cookouts. In the winter, there’s less going on. You can actually sit down with your bank statements, tax returns, and pay stubs without feeling like you’re missing out on something fun. You have the mental space to compare offers from three different lenders, to read the fine print on a loan estimate, and to ask tough questions about prepayment penalties or adjustable rates. That kind of focused attention is rare, and it’s exactly what you need to avoid getting ripped off.
So if you’ve been waiting for “the right time” to find your best mortgage deal, stop waiting. The right time might be right now, while the snow is falling and the air is cold. Use the quiet season to your advantage. Talk to a local lender, ask for a rate quote, and compare it with what a big online bank offers. Negotiate. Look at homes that others are ignoring. You’ll likely find that the best mortgage deal isn’t the one you grab in the middle of summer. It’s the one you carefully lock in during winter when no one else is paying attention.